Quant Letter

September 2026, Week 4

Weekly quantitative finance research: 90 papers from arXiv, SSRN and RePEc, 19 Sep to 25 Sep 2026.

Draft: ranked and summarised by the keyword heuristic (run with --no-llm).

arXiv

Quantitative finance and ML-for-finance preprints
02

Hierarchical Multi-Task Learning with Liquidity-Aware Signals for Stock Forecasting

To address these limitations, we propose LiMT, a Hierarchical Multi-Task Learning framework that integrates liquidity-aware signals for stock price forecasting.

2026-09-22Econometrics & Forecastingfanfare 4

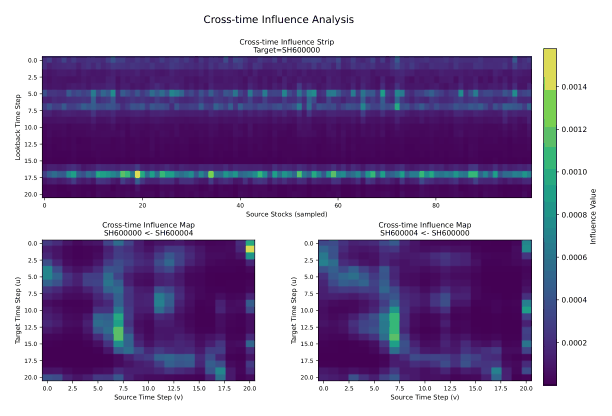
Fig. 3. Cross-time propagation heatmap at the last timestamp. The x-axis shows 100 sampled stocks, and the y-axis shows
Fig. 3. Cross-time propagation heatmap at the last timestamp. The x-axis shows 100 sampled stocks, and the y-axis shows the 21-day lookback window on March 20, 2020.
04

Universal Diffusion Models for Implied Volatility Surfaces: Learning Shared Dynamics Across Stocks

We develop a universal conditional diffusion model that learns to jointly generate next-day IVS increments and the underlying stock's returns.

2026-09-19Derivatives & Volatilityfanfare 4

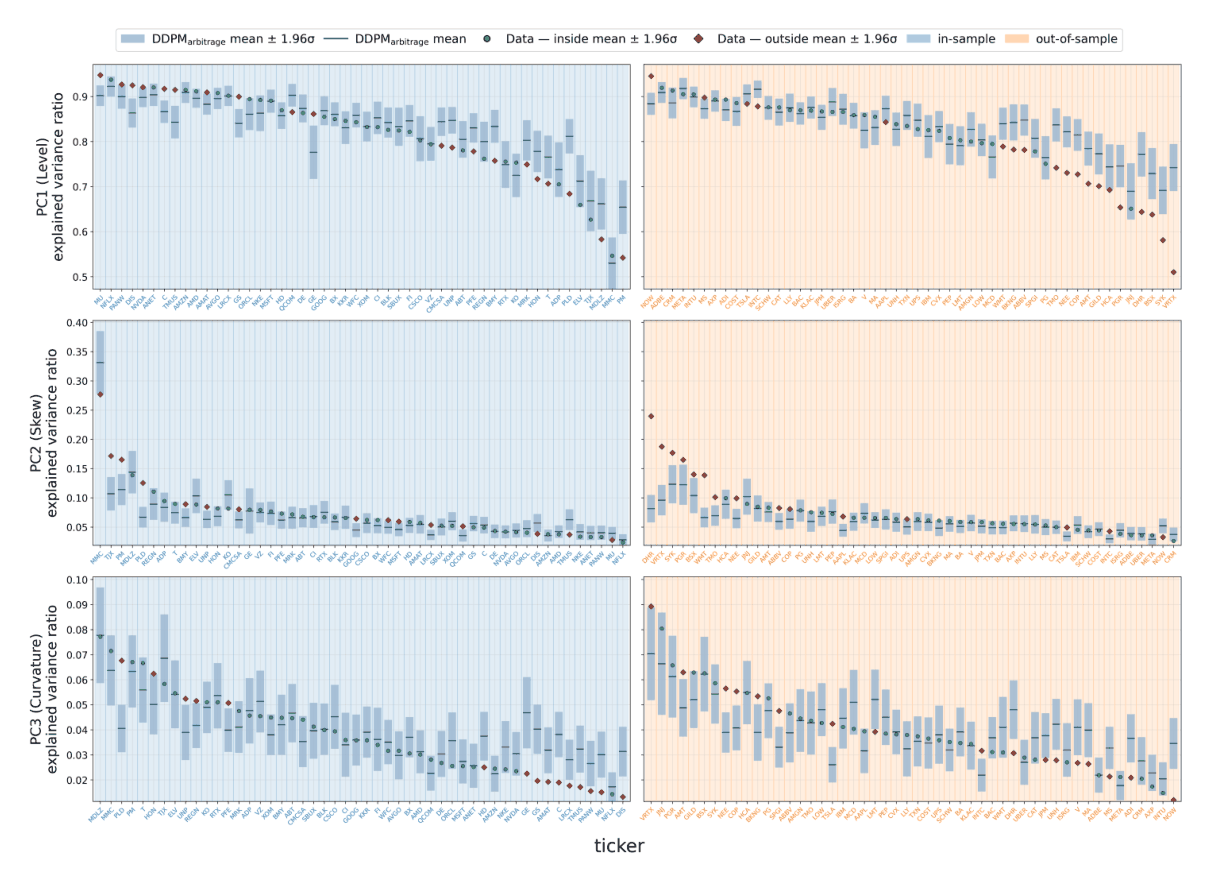
Figure 4: Stock-level comparison of observed and generated explained variance ratios for DDPMarbitrage under one-step co
Figure 4: Stock-level comparison of observed and generated explained variance ratios for DDPMarbitrage under one-step conditional generation. The top, middle, and bottom rows report PC1 (level), PC2 (skew), and PC3 (curv…
05

Artificial Intelligence in Equity and Crypto Markets: Progress, Profitability Evidence, and the Limits of Automated Investing

Artificial intelligence (AI) now supports investment workflows from data and prediction through research, portfolios, execution, and tool use.

2026-09-04Crypto & DeFifanfare 4

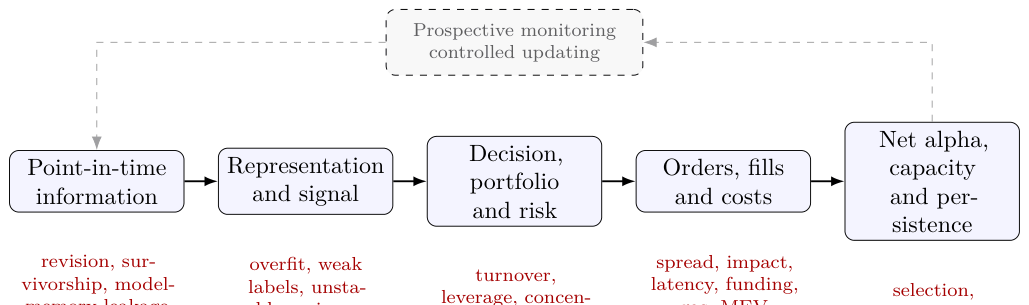
Figure 1: The alpha-translation chain. Technical improvement at one stage is economically valuable only to the extent th
Figure 1: The alpha-translation chain. Technical improvement at one stage is economically valuable only to the extent that information survives all downstream transformations. Red labels identify representative failure c…
07

Simple Dynamic Stock/Bond/Gold Portfolios

Over the 20--year period 2006--2026, using a conservative estimate of trading costs, we show that all risk-adjusted and drawdown metrics are improved using simple volatility control, where we dynamically mix the fixed-weight portfolios with cash…

2026-09-07Portfolio & Allocationfanfare 4

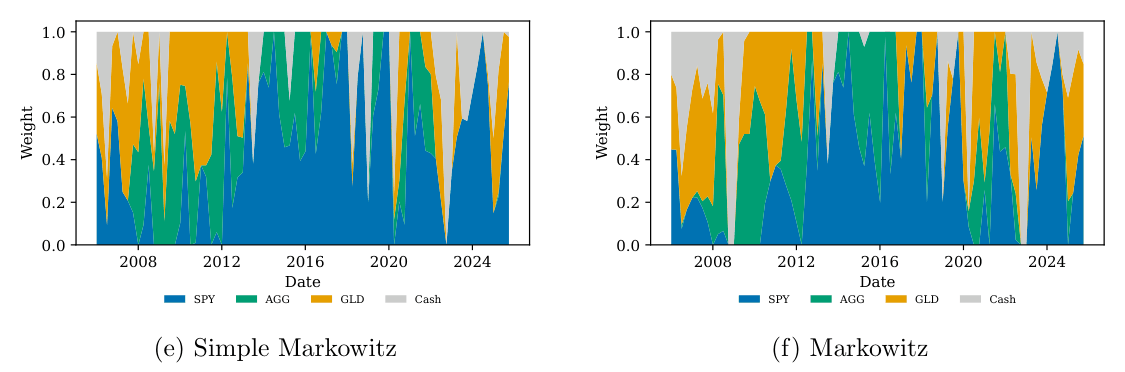
Figure 3: Portfolio weights over time.
08

Surface-Driven Stochastic Volatility for Commodity Options: Identification of Stochastic Vol-of-Vol and Leverage from Smile Dynamics

We develop a surface-driven stochastic-volatility framework for soybean futures options using daily Chicago Mercantile Exchange Group Volatility Index (CME CVOL) indicators from October 2013 to August 2025.

2026-09-22Derivatives & Volatilityfanfare 3

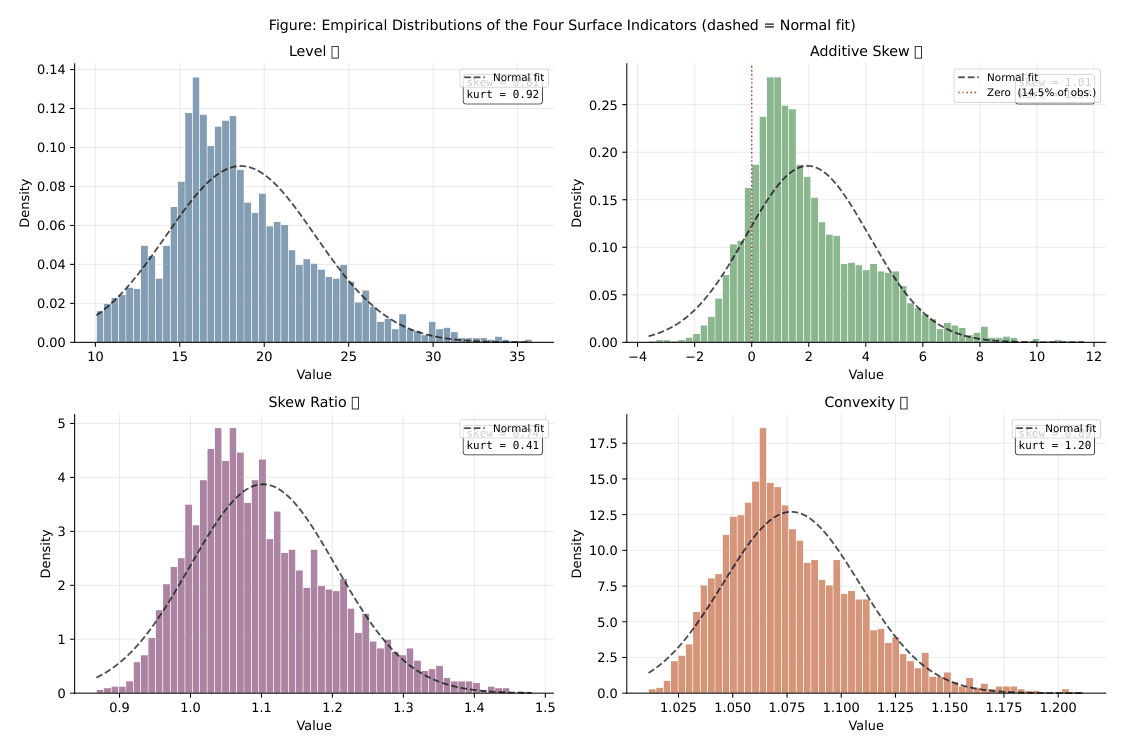
Figure 2. Empirical density histograms for the four surface indicators, with a fitted Gaussian curve for comparison. The
Figure 2. Empirical density histograms for the four surface indicators, with a fitted Gaussian curve for comparison. The red dotted vertical line in the additive-skew panel marks zero, and the annotation reports the shar…
09

Active Portfolio Management in Concentrated Equity Markets

Using historical S&P 500 data, we show that a mean-reverting SDD specification reproduces several empirical features of market diversity and dispersion.

2026-09-22Portfolio & Allocationfanfare 3

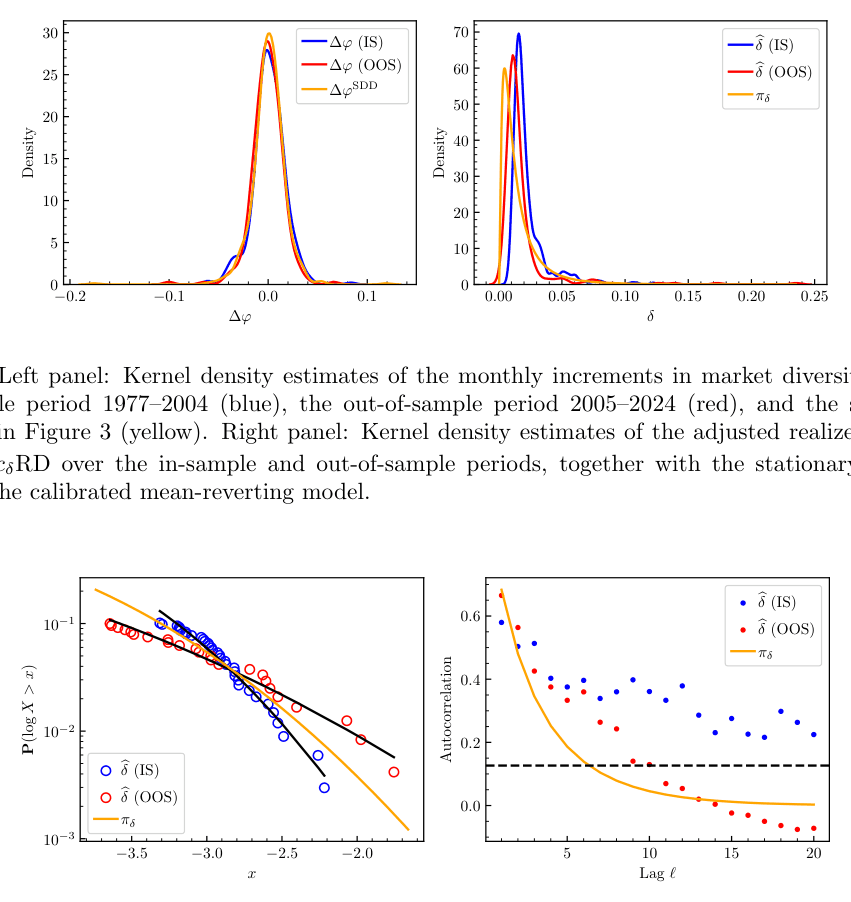
Figure 4. Left panel: Kernel density estimates of the monthly increments in market diversity, ∆φ, over the in-sample per
Figure 4. Left panel: Kernel density estimates of the monthly increments in market diversity, ∆φ, over the in-sample period 1977–2004 (blue), the out-of-sample period 2005–2024 (red), and the sample path highlighted in F…
10

CAST: A Cross-Asset State-Space Trading System for Drawdown Control in Stock Markets

We propose a cross-asset state-space trading system (CAST), consisting of two components: The predictor, Cross-Asset Collaborative Kalman Filter (CoKF), estimates each asset's latent state online, coupling all assets through their correlations and adaptively fusing multiple…

2026-09-13Trading, Microstructure & Executionfanfare 3

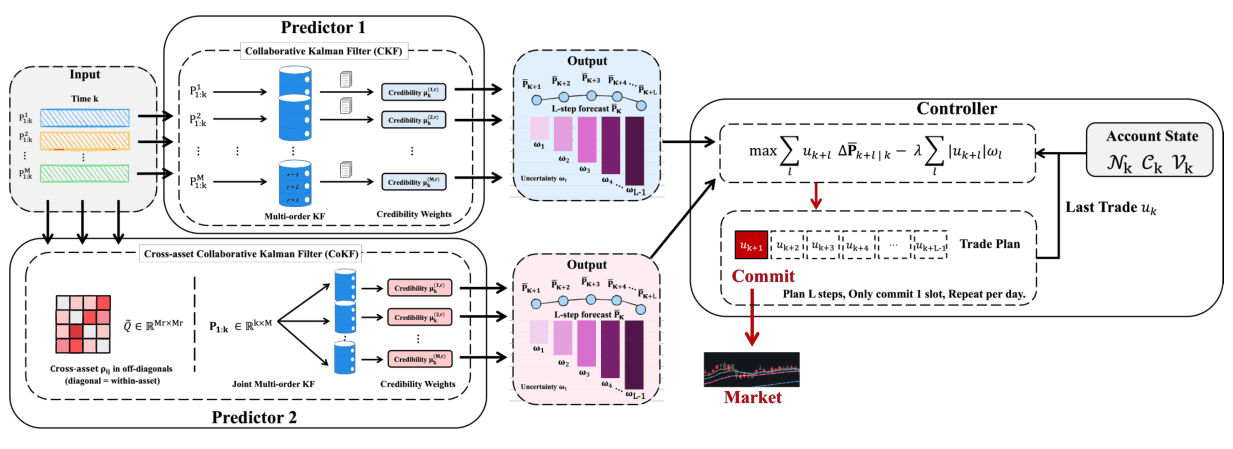
Fig. 2. Overall framework of CAST. Two predictors are shown: CKF (Multi-order, Asset-independent) and CoKF (Joint multi-
Fig. 2. Overall framework of CAST. Two predictors are shown: CKF (Multi-order, Asset-independent) and CoKF (Joint multi-order, Cross-Asset), which couples assets through the process-noise covariance e Q with off-diagonal…
12

Diffusion models for dynamic volatility surface generation and data-driven hedging

We develop a diffusion-model framework for dynamic implied-volatility surface generation and evaluate its economic usefulness through data-driven hedging.

2026-09-11Derivatives & Volatilityfanfare 3

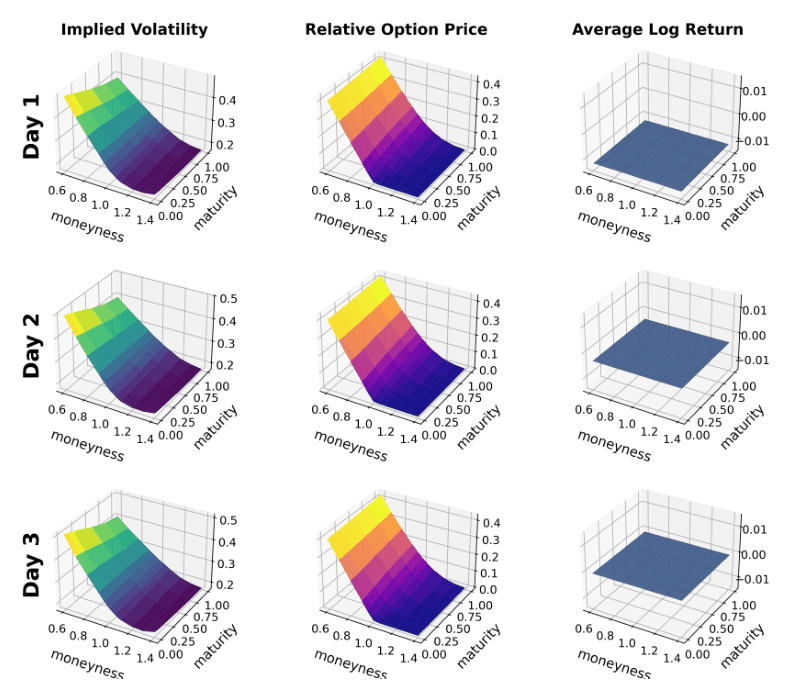
Figure 2: A generated three-day trajectory of SPX implied-volatility surfaces (left), induced relative call-price surfac
Figure 2: A generated three-day trajectory of SPX implied-volatility surfaces (left), induced relative call-price surfaces (middle), and log-return channels (right). Each row corresponds to one day. The log-return channe…
13

Optimal Investment and Consumption in Financial Markets with Integrated Variance Clocks

We study the infinite-horizon optimal investment and consumption problem in a general class of continuous financial markets, where uncertainty is driven by a continuous non-decreasing stochastic clock representing accumulated variance.

2026-09-22Derivatives & Volatilityfanfare 3

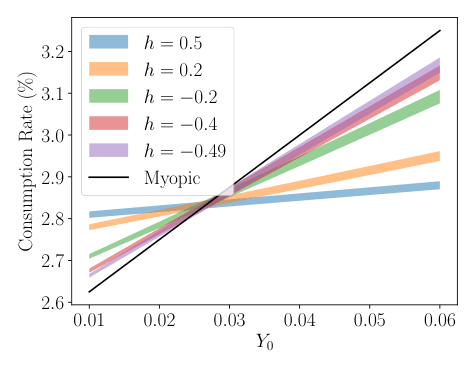
Figure 5.1: Upper and lower bounds on the optimal consumption rate at t = 0. The slope increases as h decreases.
14

Modeling interest rate swap volatility with GARCH processes

We examine the conditional volatility dynamics of the USD 1Yx10Y forward swap rate using GARCH(1,1), GJR-GARCH(1,1), and a two-regime Markov-switching GARCH (MSGARCH) model.

2026-09-22Derivatives & Volatilityfanfare 3

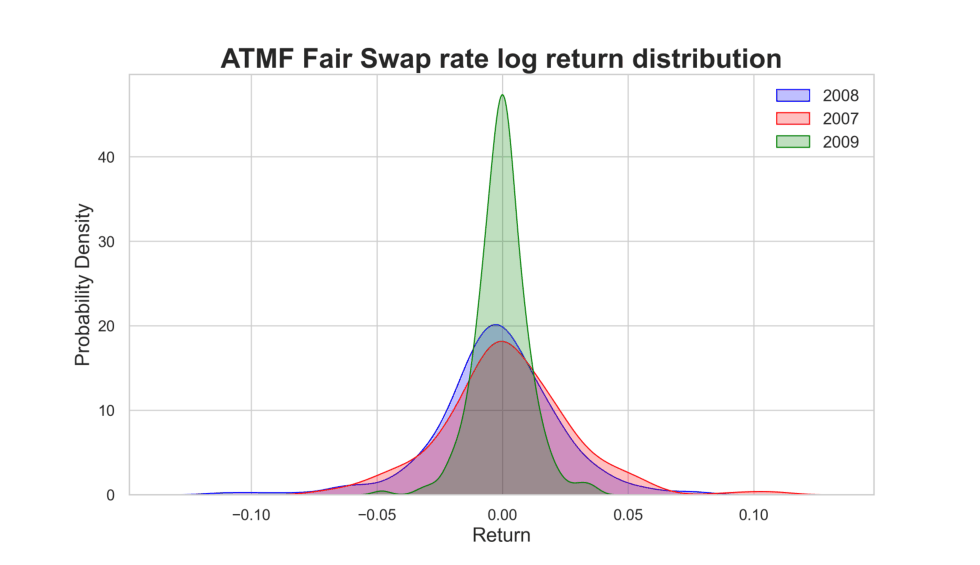
Figure 2.: Distribution of Swap Rate log return for 2007, 2008 and 2009.
15

Propose, Don't Judge: An Anytime-Valid Referee for LLM Agents That Mine Investment Factors

We cross three proposers (a script, a bandit and a language model) with this referee and with three deliberately leaky ones, in a synthetic world with planted truth, a probe-authoring environment and a ten-year walk-forward…

2026-09-22LLMs & Textfanfare 3

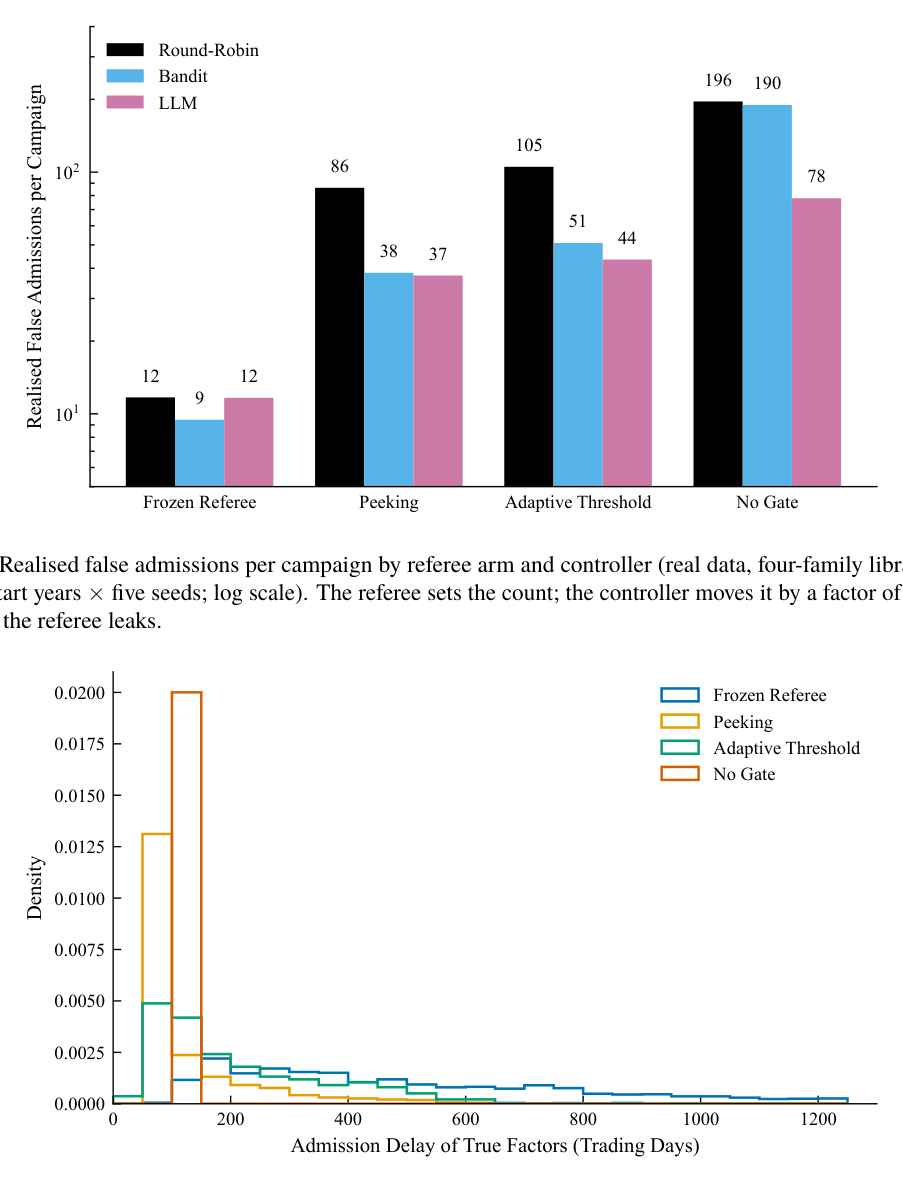
Figure 6: Realised false admissions per campaign by referee arm and controller (real data, four-family library; means ov
Figure 6: Realised false admissions per campaign by referee arm and controller (real data, four-family library; means over four start years × five seeds; log scale). The referee sets the count; the controller moves it by…
17

InvestorNerd: An Investment and Financial Insights System Based on User Profiles

InvestorNerd is a web-based platform (investornerd.org) designed to educate and democratize financial understanding by providing accessible, AI-powered investment and personal finance insights tailored to potential user profiles.

2026-09-21LLMs & Textfanfare 3

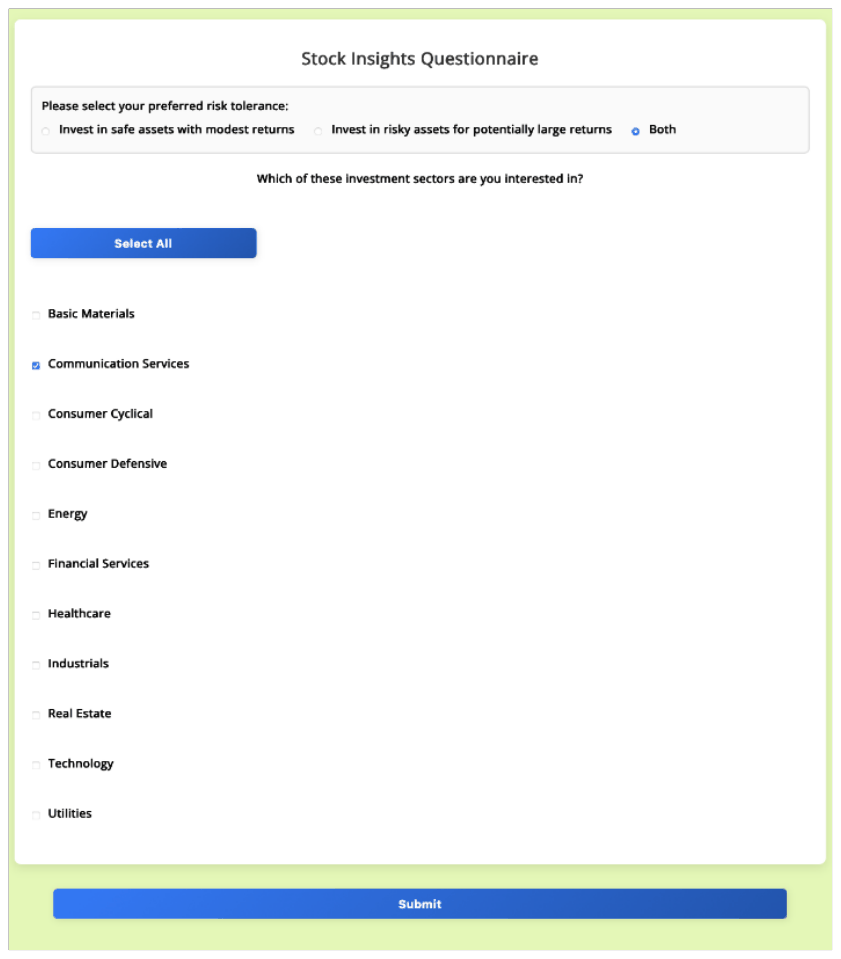
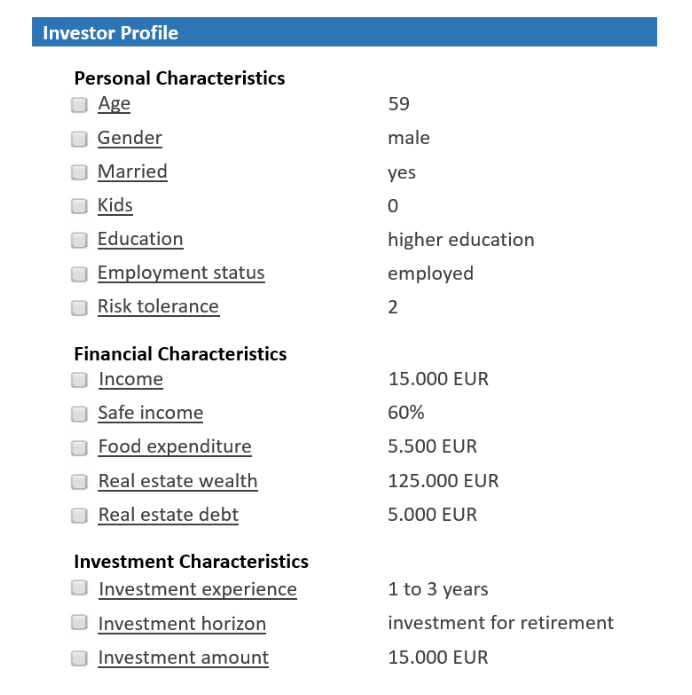
Figure 6: This is a completed questionnaire for a user who is interested in communication services stocks across risk le
Figure 6: This is a completed questionnaire for a user who is interested in communication services stocks across risk levels.
18

Compliant AI Infrastructure for Regulated Finance: A tiered multi-agent framework with DLT audit trails for financial operations in DACH

We present a compliance-first architecture for AI in regulated finance that treats regulation as an orientation layer rather than a deterministic ruleset.

2026-09-23Trading, Microstructure & Executionfanfare 3

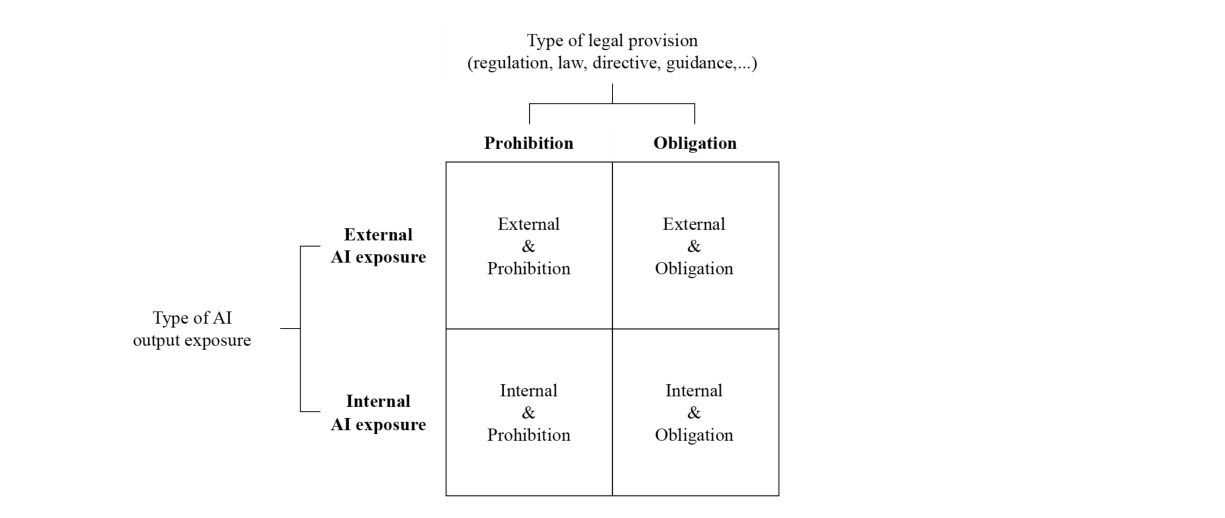
Figure 3: Regulatory intent and exposure matrix. Quadrants orient reasoning and suggest candidate guard families and evi
Figure 3: Regulatory intent and exposure matrix. Quadrants orient reasoning and suggest candidate guard families and evidence expectations. Mixed workflows default to external.
20

Liquidity Provision and Rebate Design in Option Markets

To this end, we propose a three-step rebate design scheme with flexibility to accommodate specific liquidity targets imposed by an exchange.

2026-09-22Derivatives & Volatilityfanfare 3

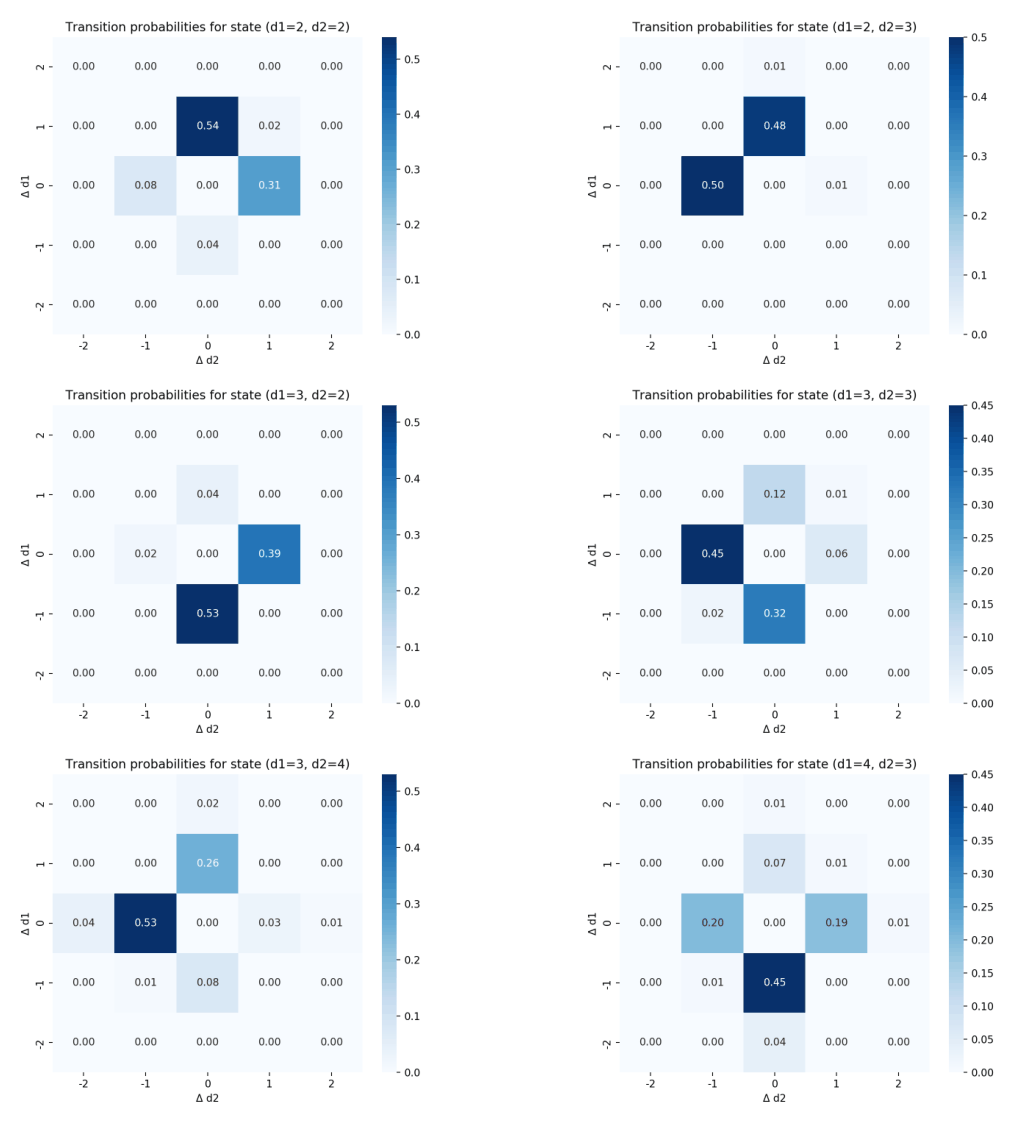
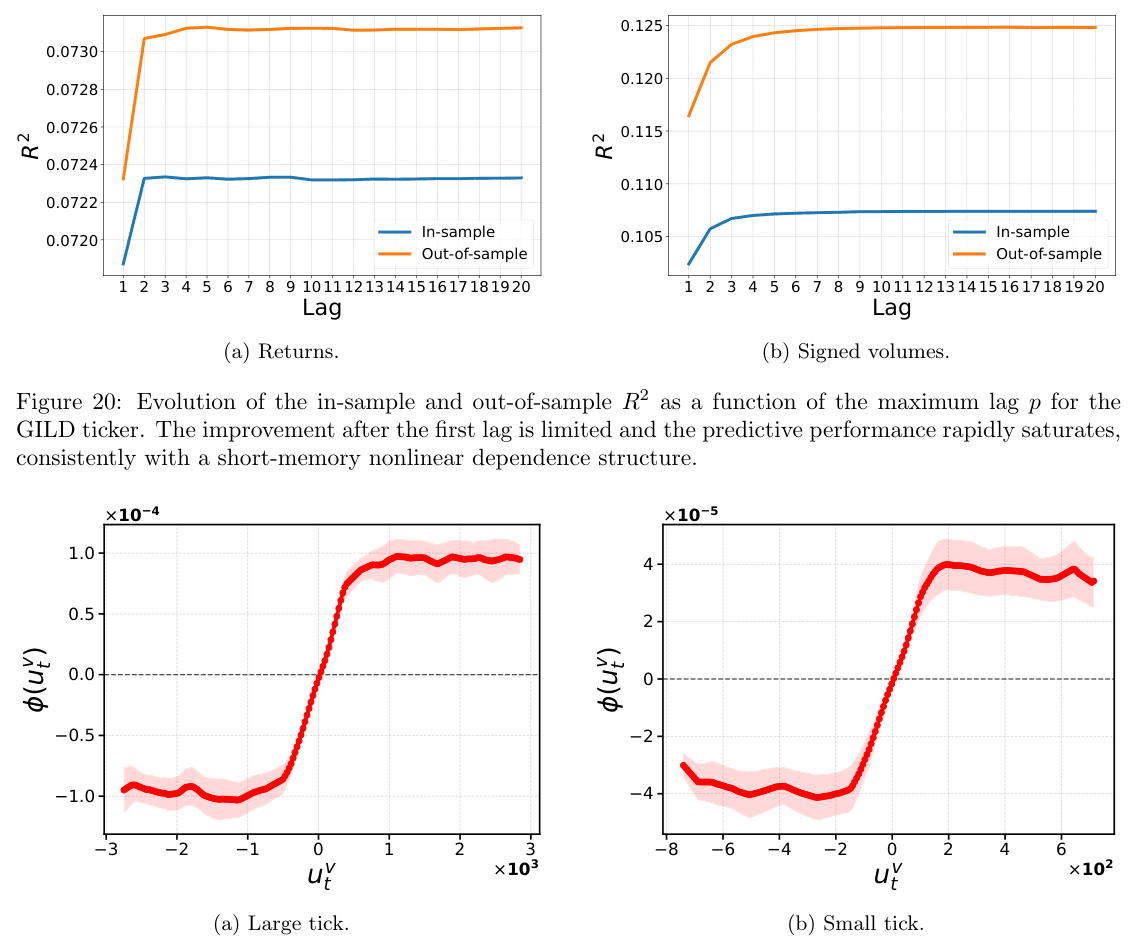
Figure 5: Plots of the estimated transition probabilities, expressed in ticks and second−1.
22

FinRankGRPO: Optimizing LLMs for Listwise Financial Asset Ranking via Group Relative Policy Optimization

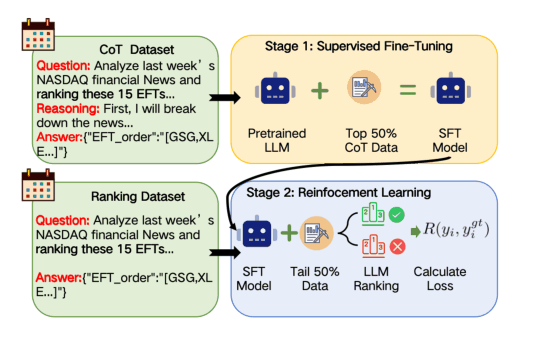
To bridge this gap, we propose FinRankGRPO, a framework that shifts LLM based portfolio construction from direct numerical prediction to listwise ranking of financial assets.

2026-09-21LLMs & Textfanfare 3

Figure 2: The two-stage construction framework of our FinRankGRPO, Stage 1 is SFT in high quality distill CoT datasets,
Figure 2: The two-stage construction framework of our FinRankGRPO, Stage 1 is SFT in high quality distill CoT datasets, Stage 2 is trained by our FinRankGRPO, which is a Spearman-related ranking reward.
24

WaVeFuse: Regime-Adaptive Equity Index Forecasting via Channel-Wise Wavelet Denoising and Vertical Attention Fusion

Hybrid Deep Learning for equity index forecasting is limited by three problems: propagation of OHLCV noise into derived technical indicators (TIs), channel-indiscriminate multi-scale decomposition that conflates heterogeneous frequency signatures, and static multi-branch fusion that cannot…

2026-09-13Econometrics & Forecastingfanfare 3

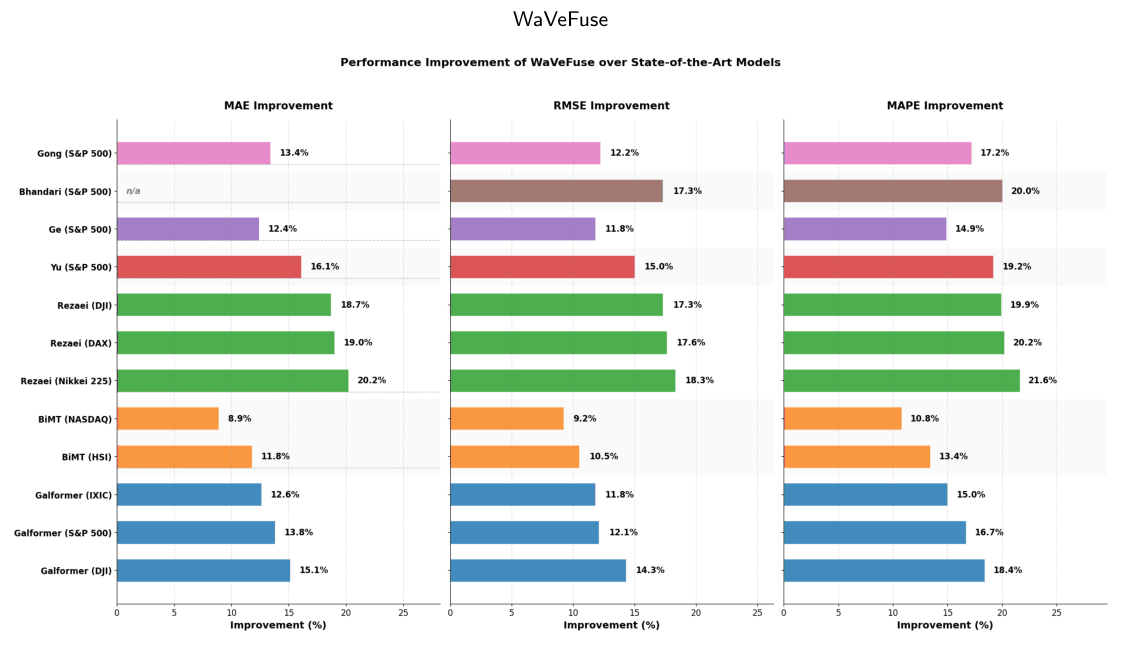
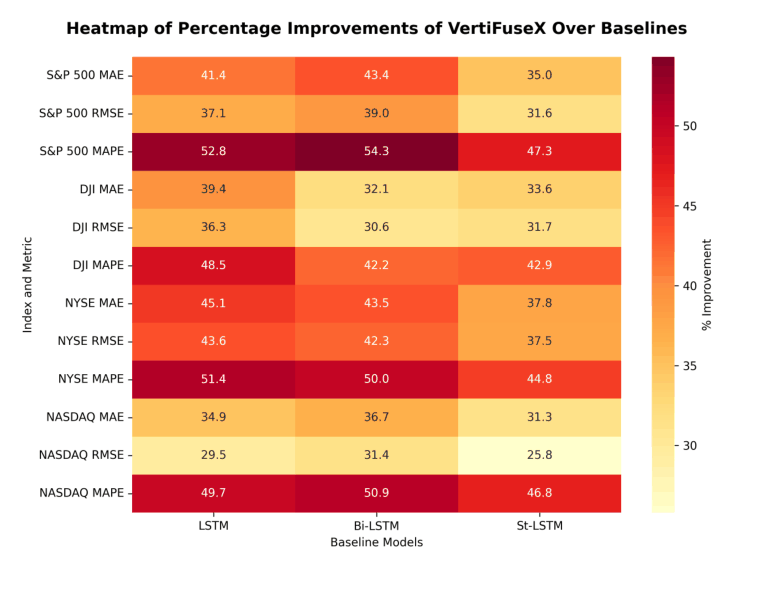
Figure 10: Relative performance improvement (%) of WaVeFuse over seven state-of-the-art models (and their specific index
Figure 10: Relative performance improvement (%) of WaVeFuse over seven state-of-the-art models (and their specific index/dataset configurations) on MAE, RMSE, and MAPE. Improvements are computed against the originally re…
26

Principal component error in high-dimensional factor models

We write the often substantial error in these estimates as a sum of two interpretable terms, which we show have almost sure asymptotic limits as the number of variables grows with sample size bounded.

2026-09-17Asset Pricing & Factorsfanfare 3

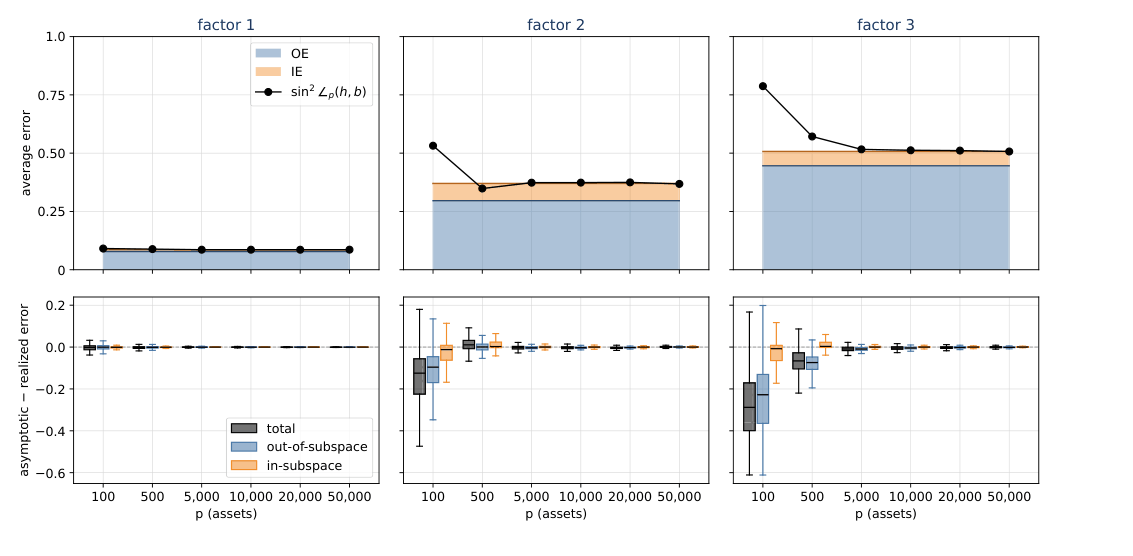
Figure 1: Error in principal directions estimated from n = 63 observations based on 1000 simulations. The x-axis is the
Figure 1: Error in principal directions estimated from n = 63 observations based on 1000 simulations. The x-axis is the number of variables p. Top panel: The y-axis is average error in units of sin2
27

Deep Learning of Robust Market Making under Regime-Switching Order Flow

In this paper, we develop a deep reinforcement-learning market maker (RLMM) - a Rainbow-style distributional DQN (C51) which is calibrated and tested in a zero-intelligence limit order book.

2026-09-10Trading, Microstructure & Executionfanfare 3

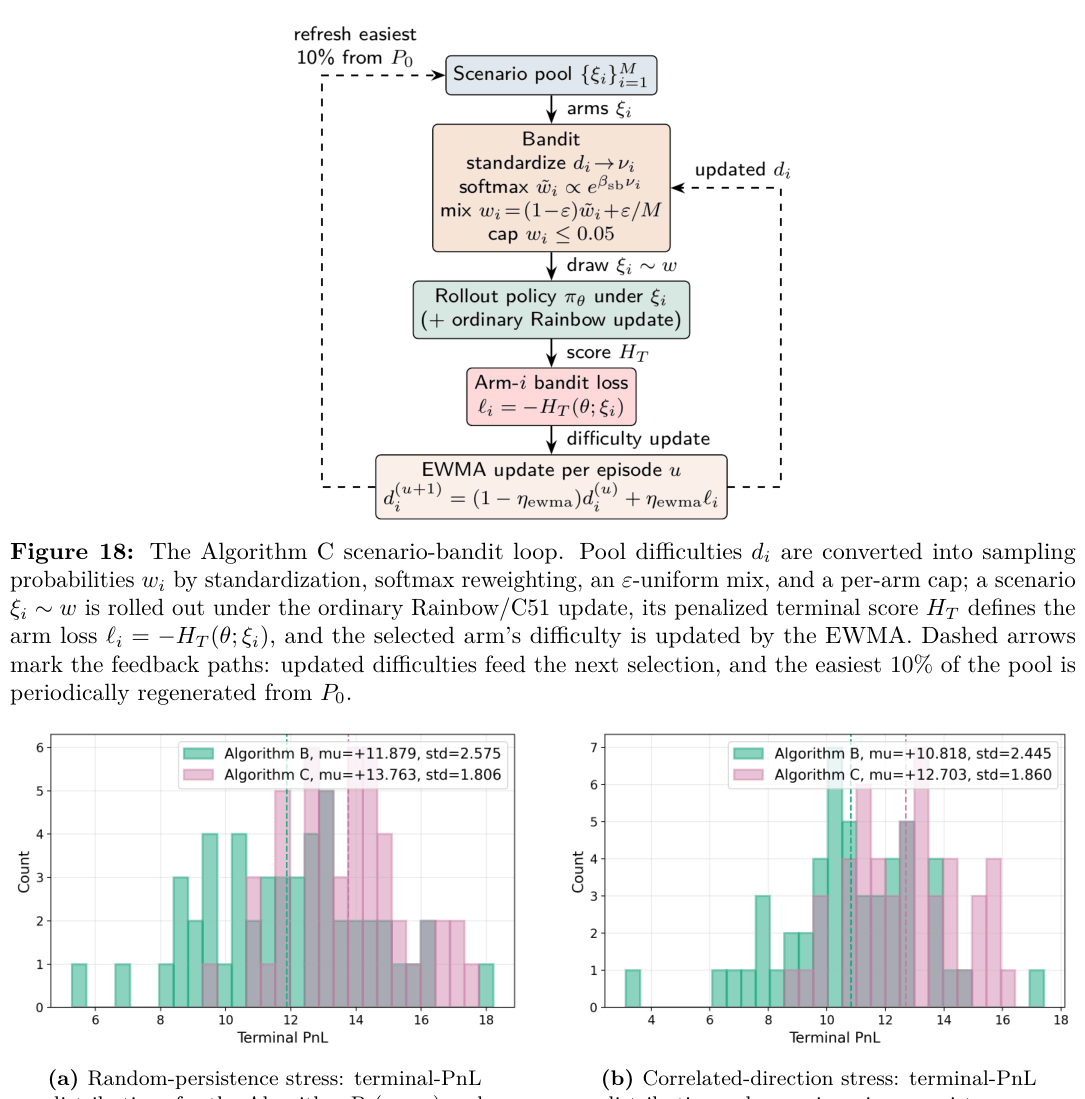
Figure 18: The Algorithm C scenario-bandit loop. Pool difficulties di are converted into sampling probabilities wi by st
Figure 18: The Algorithm C scenario-bandit loop. Pool difficulties di are converted into sampling probabilities wi by standardization, softmax reweighting, an ε-uniform mix, and a per-arm cap; a scenario ξi ∼w is rolled …

SSRN

New working papers in finance, economics and ML
20

Multivariate Stochastic Volatility with Machine Learning-Augmented Regime Detection for Cross-Market Financial Contagion: A Bayesian Nonparametric and Ensemble-Learning Comparative Framework

This paper extends the empirical framework of Christopher (2026), which documents a 49% contagion intensification between the S&P 500 and Nifty 50 during joint high-volatility regimes using GJR-GARCH and rolling-threshold regime classification, along two dimensions…

2026-09-21Derivatives & Volatilityfanfare 3

21

Generative Capital: Foundations of AI-Native Personal Finance

This paper introduces Generative Capital, a financial architecture that integrates tokenization, decentralized finance, artificial intelligence, quantitative portfolio construction and agents: (i) eligible assets are digitally represented and divisible, (ii) only assets, and counterparties, that pass…

2026-09-23Crypto & DeFifanfare 3

RePEc

Working papers curated by RePEc's NEP field reports
03

Forecasting Inflation in Tunisia Using Machine Learning Methods

Forecasting inflation in the presence of changing economic conditions, external shocks, and evolving transmission mechanisms remains an active area of research.

2026-09-14Macro-Finance & Ratesfanfare 2

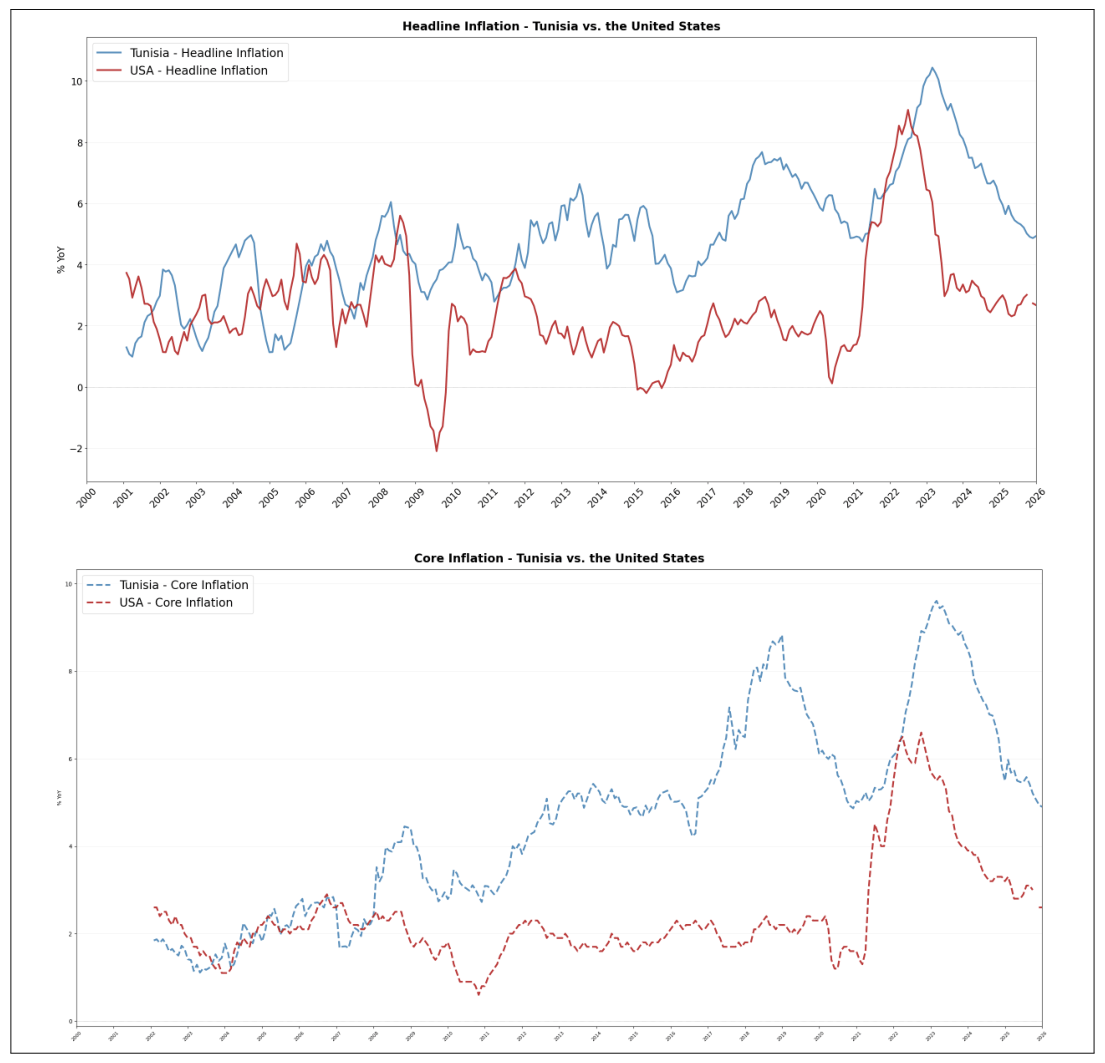
Figure 1: Inflation Dynamics in Tunisia vs. the United States Note: Monthly year-on-year (YoY) inflation rates for Tunis
Figure 1: Inflation Dynamics in Tunisia vs. the United States Note: Monthly year-on-year (YoY) inflation rates for Tunisia and the United States over the sample
08

Regimes, Not Forecasts: Reassessing Dynamic Nelson-Siegel Term Structure Forecasting, and a Proposed Descriptive Alternative

Rather than treat this as a dead end, this paper develops and formally tests an alternative: a small number of recurring, economically interpretable curve-shape states — fewer in number than they first appear, once rate…

2026-09-14Econometrics & Forecastingfanfare 2

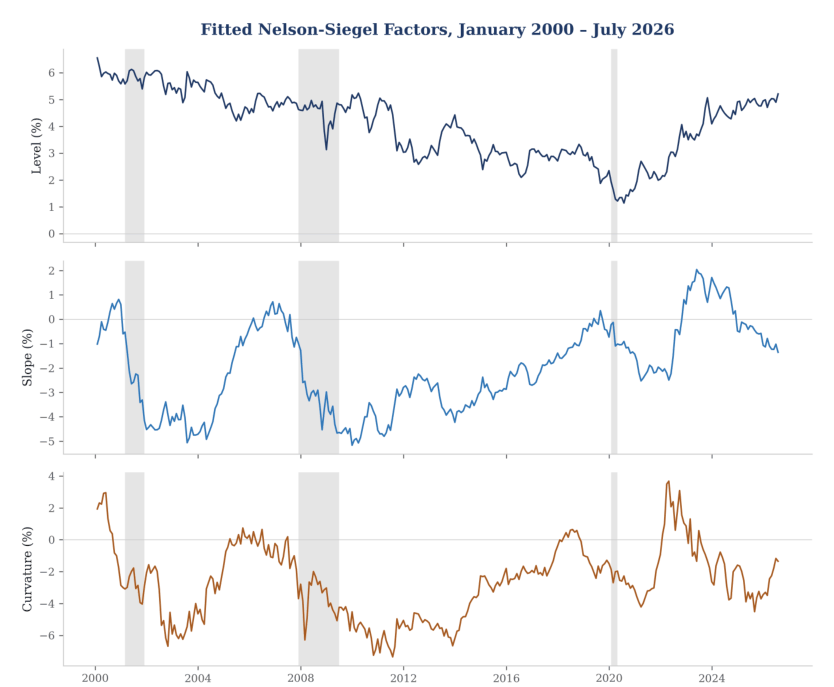
Figure 1. Fitted Level, Slope, and Curvature, January 2000 – July 2026. Shaded bands mark NBER recession dates.
09

Prices and Monetary Policy: The Role of Financial Constraints

Using detailed microdata on Swedish public and private firms, and high-frequency monetary policy surprises around Riksbank announcements, we document that smaller, financially constrained firms adjust prices significantly less than larger firms in response to changes…

2026-09-14Macro-Finance & Ratesfanfare 2

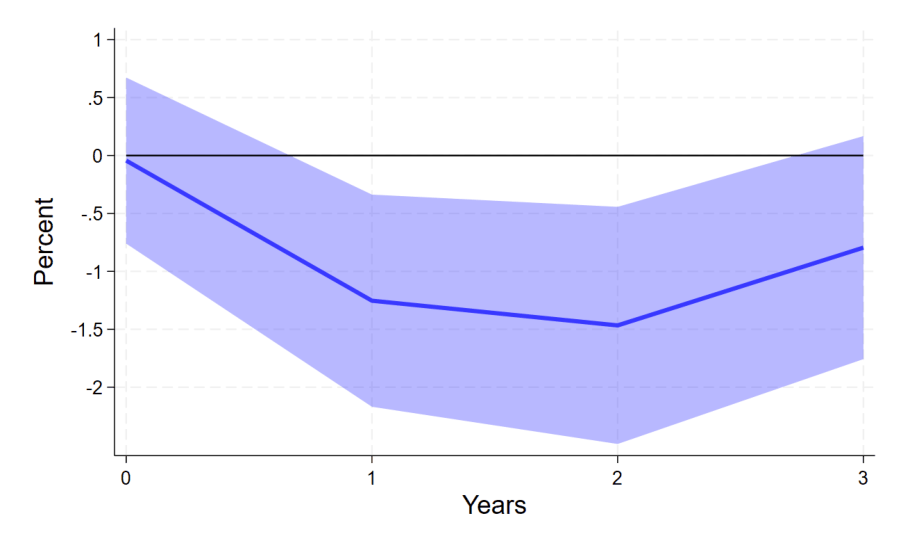
Figure 7: Differential Debt Response by Firm Size
13

Demand for Dollars: Evidence from Survey Expectations

We study the determinants of US dollar demand across market participants and traded instruments using survey-based exchange rate and macroeconomic expectations.

2026-09-14Trading, Microstructure & Executionfanfare 2

14

Stablecoins Meet the Mundell–Fleming Trilemma

We study how stablecoins impact global capital flows by constructing a novel wallet-level dataset linking geotagged Ethereum Name Service registrations to stablecoin transactions around banking restrictions, currency crises, sanctions, and monetary disruptions.

2026-09-14Crypto & DeFifanfare 2

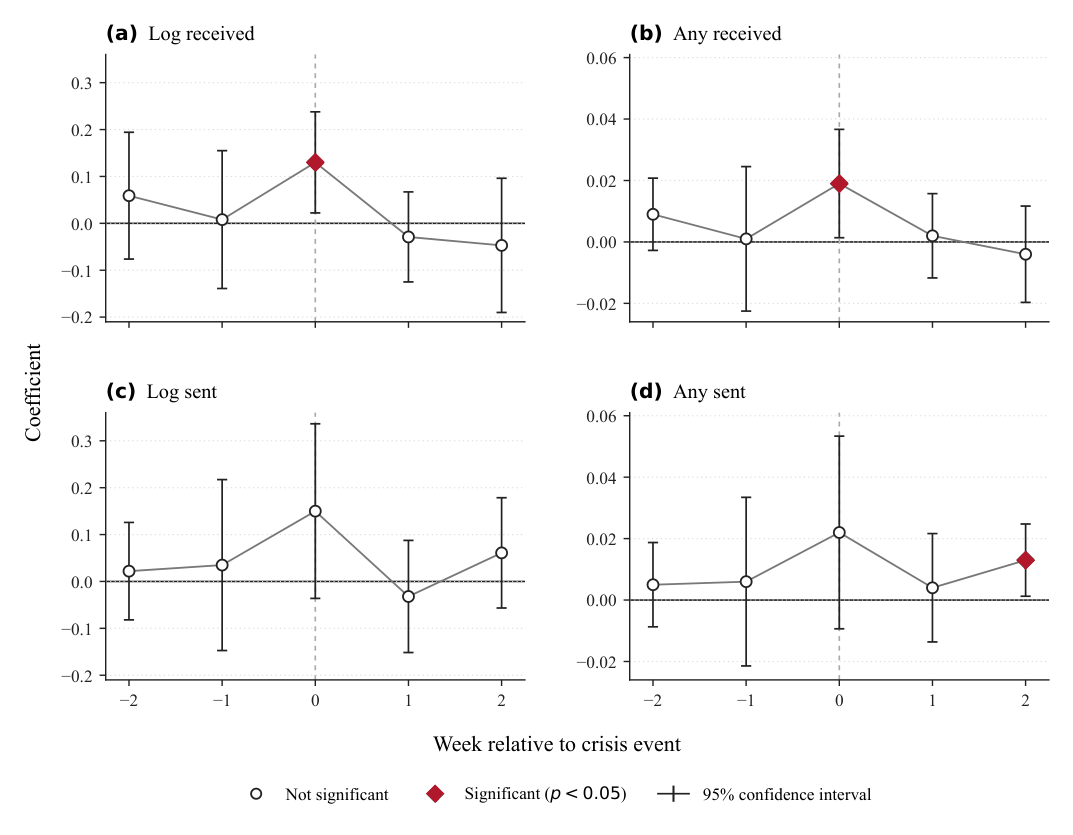
Figure 5: Stablecoin activity around crisis events by country-tag status. This figure reports event-time coefficients fo
Figure 5: Stablecoin activity around crisis events by country-tag status. This figure reports event-time coefficients for the interaction between country-tag treatment status and weeks relative to the crisis event. Panel…
15

Financial Interdependence and Currency Internationalization

To study the competition between incumbent and rising powers under financial interdependence, we develop a model of asset demand with microfounded network effects.

2026-09-14ML & AI Methodsfanfare 2

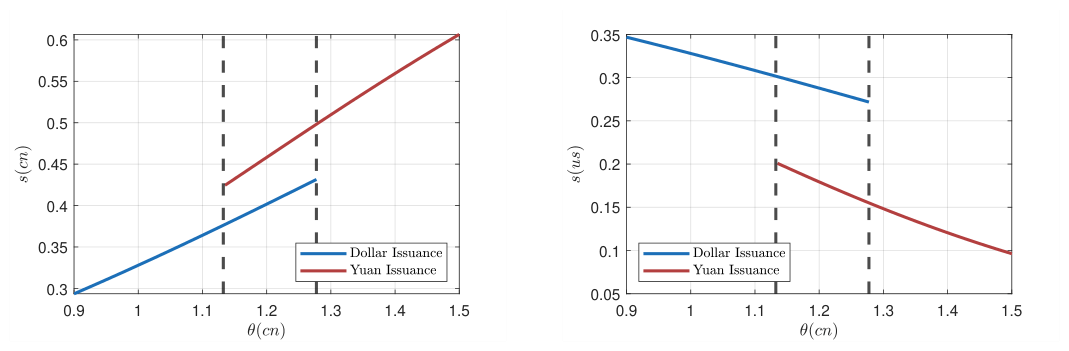
Figure 4: Multiple Equilibria with Three Countries
18

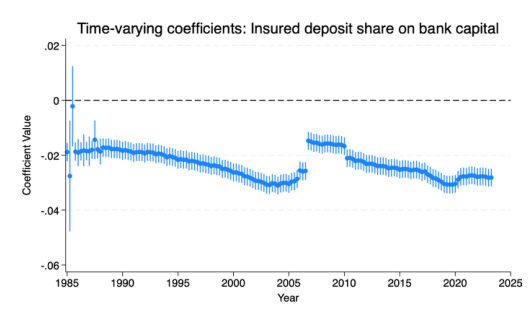
Bank Capital and Deposit Insurance

This paper examines the relationship between bank capital and reliance on insured deposit funding.

2026-09-14Risk, Credit & Bankingfanfare 2

Figure 1: Negative correlation between the share of insured deposits and bank capital in the (a) cross section and (b) p
Figure 1: Negative correlation between the share of insured deposits and bank capital in the (a) cross section and (b) panel over the sample period.
25

What determines banks' excess demand for reserves?

Using granular data, we document significant fragmentation in interbank markets with a set of banks that never trade in interbank markets (inactive banks) and others that do (active banks).

2026-09-21Risk, Credit & Bankingfanfare 2

27

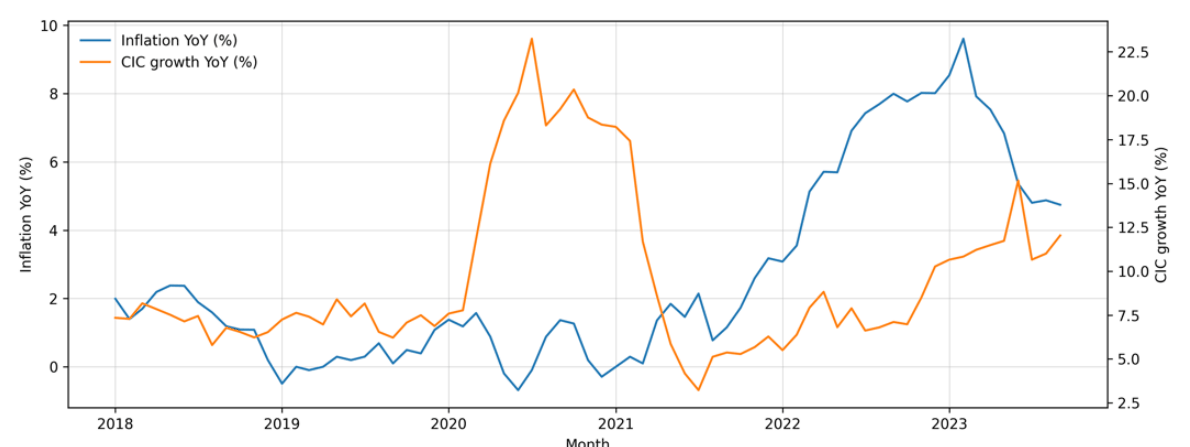
Cash in circulation and inflation in Morocco: Causality and economic impact

This paper examines whether changes in cash in circulation contain predictive content for inflation in Morocco, and whether inflation itself feeds back into cash demand, during a period marked by major shocks (2017M01-2023M09).

2026-09-14Macro-Finance & Ratesfanfare 2

Figure 2 Descriptive dynamics of CPI inflation (YoY) and cash in circulation growth (YoY) in Morocco.
28

Reconstructing a Century of U.S. Corporate Bonds: Credit Risk in Historical Perspective

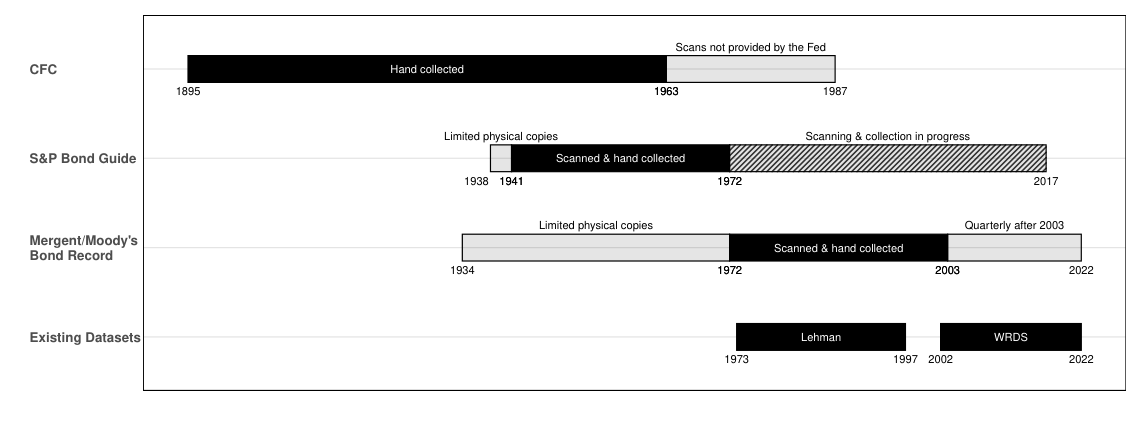
We construct a new historical corporate bond database spanning 128 years to estimate a corporate bond counterpart to the equity risk premium.

2026-09-07Risk, Credit & Bankingfanfare 2

Figure 1: Coverage of the new corporate bond database. This figure illustrates the construction of our historical corpor
Figure 1: Coverage of the new corporate bond database. This figure illustrates the construction of our historical corporate bond database, showing data coverage periods for five sources: (i) Commercial and Financial Chro…
30

Political Communication and Cryptocurrency Volatility. Level Effects and Regime Transitions at High Frequency

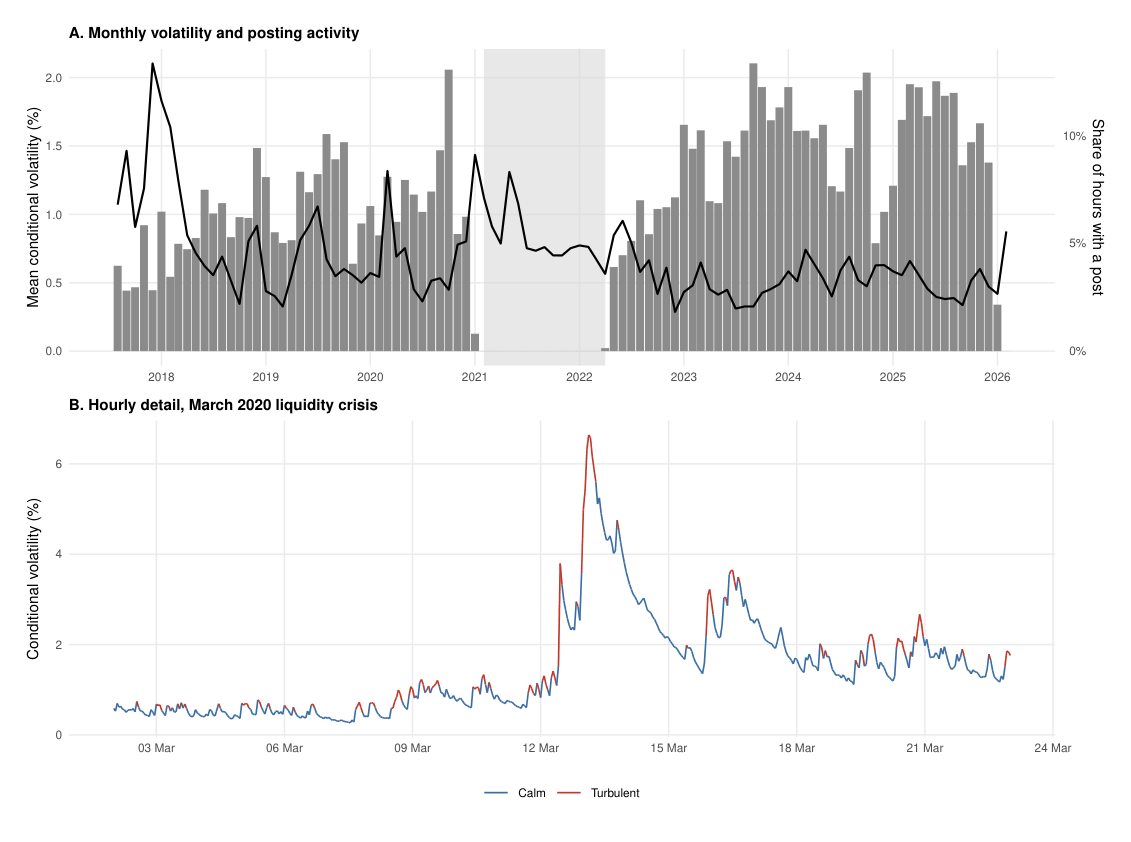
We ask whether high-frequency political communication shapes the level of conditional volatility, its persistence, or the probability of transiting between volatility states.

2026-09-07Crypto & DeFifanfare 2

Figure 1: Conditional volatility from the MS-EGARCH-X. Panel A: monthly mean conditional volatility (black line, left ax
Figure 1: Conditional volatility from the MS-EGARCH-X. Panel A: monthly mean conditional volatility (black line, left axis) and share of hourly windows containing at least one market-relevant post (grey bars, right axis)…